

ARTICLES & GUIDES
How to Buy a Car Without Getting Taken For a Ride
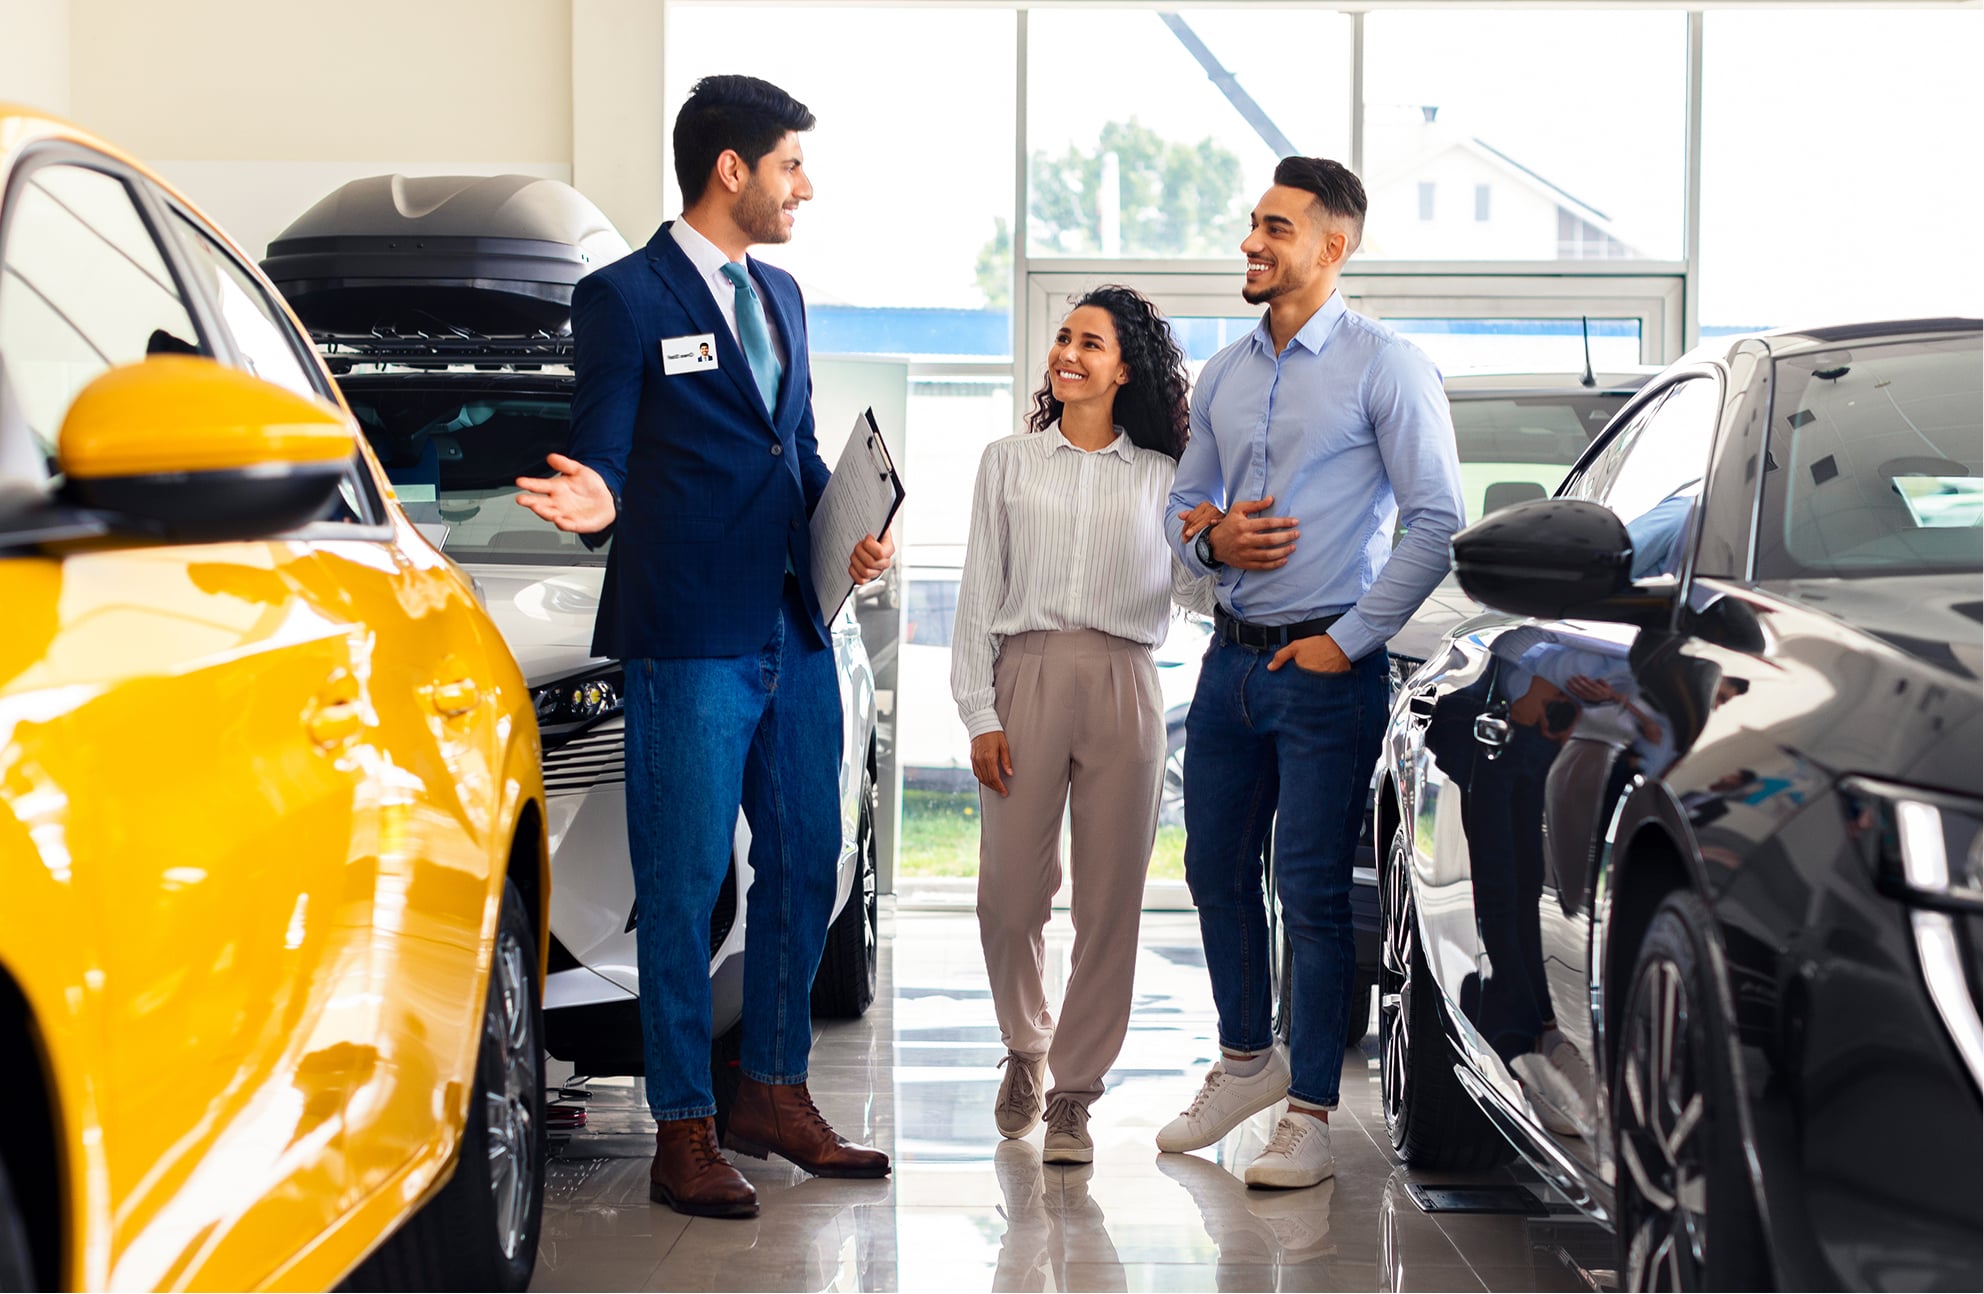
A customer and a car dealer usually have conflicting goals during the sales process. The customer wants to pay as little as possible, whereas the car dealer wants to make as much profit as possible. To maximize its profits, a car dealer frames the negotiations and sale in a way that is favorable to it. Here are some ways to turn the tables on the car dealer:
- Negotiate the Cash Price, Not the Monthly Payment.
The salesperson usually begins the negotiation by asking you how much you want to pay or can afford to pay a month. Negotiating this way enables the salesperson to steer you into a sale that’s best for the car dealer. Instead, do your homework before you go to the dealer. For new cars, you should know what the sticker price or manufacturer’s suggested retail price (MSRP) is before you go to the dealer. You also should look for the dealer or invoice price, which reflects the amount the dealer paid for the car. There are many resources online that provide this information. Also, check the prices at different local dealers.
For used cars, you should find out the price range for the specific vehicle you are interested in, which can be done online through various websites that sell used cars or that provide the estimated or blue book value of used cars. Obtaining this information beforehand will enable you to negotiate the cash price of a vehicle effectively. Likewise, when negotiating the price, ask the dealer for the out-the-door price, which is the total cash price for a car with all charges included (such as tax, registration, and document fees). See Tips on Buying a Car During the COVID-19 Pandemic.
To increase its profit from the sale of the finance agreement, the dealer may need to charge you a higher interest rate than you could get if you obtained the financing on your own.
- Determine What Interest Rates You Are Eligible for Before You Go to the Dealer.
Part of the dealer’s strategy for increasing its profit is arranging the financing. The dealer often acts as the initial lender and then sells the finance agreement for a profit to a traditional lender. To increase its profit from the sale of the finance agreement, the dealer may need to charge you a higher interest rate than you could get if you obtained the financing on your own. Also, even if the dealer advertises a low-interest rate, you might not qualify for that rate. Therefore, find out what interest rates you qualify for and get preapproved for those rates before going to the dealer.
- Decline the Optional Products and Services.
After you’ve negotiated the sales price and the financing terms, the dealer will invariably try to sell a multitude of optional products and services: rustproofing, paint protection, fabric protection, VIN etching, oil change contracts, and extended service contracts. Not only are these options unnecessary, but they are also substantially marked up. These are a significant source of profit for dealers. If you really want these options, you can buy them elsewhere for less. Moreover, extended warranties or service contracts are usually not worth the money.
LATEST ARTICLES & GUIDES FROM OUR EXPERTS
Start Your Lemon Law Claim Today.
It’s Free and Fast.
We can tell you instantly if you may have a valid lemon case and get you started today.
ARTICLES & GUIDES
How to Buy a Car Without Getting Taken For a Ride
A customer and a car dealer usually have conflicting goals during the sales process. The customer wants to pay as little as possible, whereas the car dealer wants to make as much profit as possible. To maximize its profits, a car dealer frames the negotiations and sale in a way that is favorable to it. Here are some ways to turn the tables on the car dealer:
- Negotiate the Cash Price, Not the Monthly Payment.
The salesperson usually begins the negotiation by asking you how much you want to pay or can afford to pay a month. Negotiating this way enables the salesperson to steer you into a sale that’s best for the car dealer. Instead, do your homework before you go to the dealer. For new cars, you should know what the sticker price or manufacturer’s suggested retail price (MSRP) is before you go to the dealer. You also should look for the dealer or invoice price, which reflects the amount the dealer paid for the car. There are many resources online that provide this information. Also, check the prices at different local dealers.
For used cars, you should find out the price range for the specific vehicle you are interested in, which can be done online through various websites that sell used cars or that provide the estimated or blue book value of used cars. Obtaining this information beforehand will enable you to negotiate the cash price of a vehicle effectively. Likewise, when negotiating the price, ask the dealer for the out-the-door price, which is the total cash price for a car with all charges included (such as tax, registration, and document fees). See Tips on Buying a Car During the COVID-19 Pandemic.
To increase its profit from the sale of the finance agreement, the dealer may need to charge you a higher interest rate than you could get if you obtained the financing on your own.
- Determine What Interest Rates You Are Eligible for Before You Go to the Dealer.
Part of the dealer’s strategy for increasing its profit is arranging the financing. The dealer often acts as the initial lender and then sells the finance agreement for a profit to a traditional lender. To increase its profit from the sale of the finance agreement, the dealer may need to charge you a higher interest rate than you could get if you obtained the financing on your own. Also, even if the dealer advertises a low-interest rate, you might not qualify for that rate. Therefore, find out what interest rates you qualify for and get preapproved for those rates before going to the dealer.
- Decline the Optional Products and Services.
After you’ve negotiated the sales price and the financing terms, the dealer will invariably try to sell a multitude of optional products and services: rustproofing, paint protection, fabric protection, VIN etching, oil change contracts, and extended service contracts. Not only are these options unnecessary, but they are also substantially marked up. These are a significant source of profit for dealers. If you really want these options, you can buy them elsewhere for less. Moreover, extended warranties or service contracts are usually not worth the money.
LATEST ARTICLES AND GUIDES FROM OUR EXPERTS
Beware of Lemon Law Scams and What is Fee Shifting?
Lemon Law for Used Cars: What Buyers Need to Know About Their Rights
Lemon Law for Leased Cars: What Happens If You Still Owe on a Defective Vehicle?
Start Your Lemon Law Claim Today.
It’s Free and Fast.
We can tell you instantly if you may have a valid lemon case and get you started today.